How to Sell Your House Quickly
Need to sell house quickly? Discover proven strategies, timelines, and alternatives to traditional listings that help Indiana homeowners close fast.
Life doesn't wait for the perfect moment. When circumstances force your hand-a job relocation, financial hardship, inherited property, or divorce-the clock starts ticking. The traditional home-selling process, with its months-long timeline of repairs, staging, showings, and negotiations, suddenly feels impossible. If you need to sell house quickly, you're not alone, and you're not without options. Thousands of Indiana homeowners face this exact situation every year, navigating between the pressure of time and the desire to make smart financial decisions.
Understanding What "Quickly" Really Means
Speed means different things to different sellers. For some, quick means closing within 90 days instead of the typical six-month process. For others facing foreclosure or urgent relocation, quick means weeks, not months.
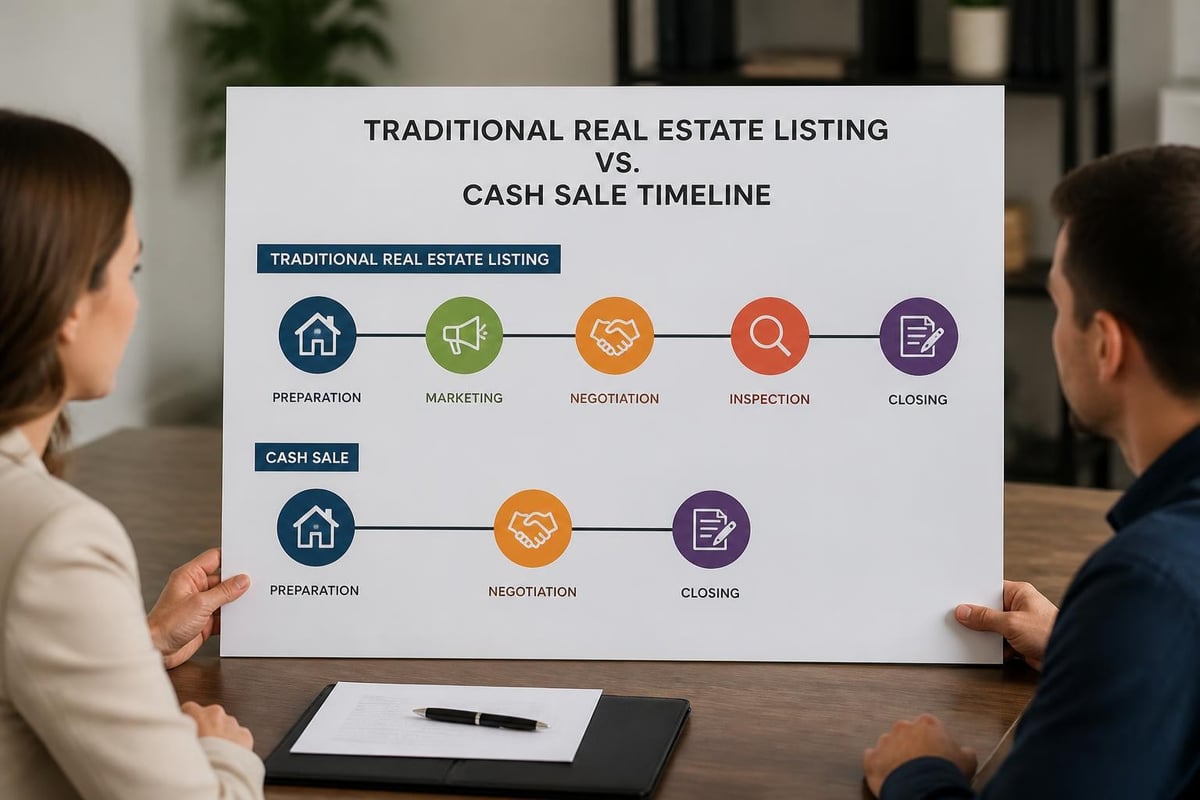
The traditional home sale timeline breaks down into predictable phases. Preparation and repairs typically consume 2-4 weeks. Marketing and finding a buyer takes another 4-8 weeks in normal markets. Then comes the inspection period, appraisal, and financing approval-another 4-6 weeks minimum. You're looking at 10-18 weeks under ideal conditions.
Setting Realistic Expectations
Markets don't care about your timeline. A seller's market in Indianapolis might move properties in 30 days, while a buyer's market could stretch that to 120 days or longer. The national median time on market fluctuates between 6-8 weeks, but local conditions vary dramatically.
Your property's condition matters more than you think. Move-in ready homes sell faster. Homes needing work sit longer, regardless of price adjustments. The neighborhood plays a role too-established communities in Hamilton County might see faster turnover than rural areas.
Why Speed Becomes Essential
Financial pressure drives many quick sales. Falling behind on mortgage payments creates a countdown to foreclosure. Property taxes accumulate. Maintenance costs don't pause while you decide what to do. An inherited property in Fort Wayne sitting empty still demands heating bills, insurance, and upkeep.
Job relocations offer no flexibility. When your employer needs you in another state within 60 days, traditional listing timelines become impossible. The stress of managing two mortgages or paying for temporary housing while your old home sits on the market creates unbearable pressure.
Divorce proceedings rarely wait for real estate markets. Courts set deadlines. Asset division requires resolution. Both parties need to move forward, making a prolonged sale process emotionally and financially draining. Similarly, health crises demand immediate action and liquid assets, not properties that might sell eventually.
The Traditional Listing Route-Accelerated
If you need to sell house quickly through traditional channels, strategic decisions make the difference. Pricing aggressively from day one matters more than any other single factor.
Preparation That Pays Off
Essential quick-turnaround improvements:
Deep cleaning every room, including carpets and windows
Fresh neutral paint over bold colors
Fixing obvious defects like broken fixtures or torn screens
Yard maintenance and enhanced curb appeal
Removing personal items and excess furniture
Minor investments yield returns. Professional photography isn't optional if you want serious buyers. Homes with professional photos sell 32% faster than those with smartphone pictures. Virtual tours expanded your buyer pool during the pandemic and remain valuable in 2026.
The showing flexibility factor cannot be overstated. Buyers operate on their schedules. Limiting showings to weekends or requiring 48-hour notice dramatically reduces your buyer pool.
StrategyTime InvestmentCostImpact on SpeedAggressive pricing1 hour$0Very HighProfessional photos2-3 hours$200-400HighDeep cleaning8-16 hours$200-500Medium-HighMinor repairsVariable$500-2000MediumStaging consultation2-4 hours$300-800Medium
Agent Selection Makes or Breaks Speed
Not all real estate agents understand urgency. Interview multiple agents specifically about their quick-sale experience. How many homes have they sold in under 30 days? What's their average days-on-market compared to the area average? Their marketing plan should include digital advertising, open houses within the first week, and aggressive outreach to their network.
Commission structure sometimes offers leverage. An agent motivated by a slightly higher commission might prioritize your listing, dedicate more resources to marketing, and push harder for quick offers. However, quality matters more than commission rates. The best agents earn their percentage by delivering results when you need to sell house quickly.
The Power of Professional Networks
Top agents maintain relationships with investors, other realtors, and serious buyers actively searching. Your property hits their network before it hits the MLS. This head start can shave weeks off the process. In markets like Carmel or Fishers, where inventory moves quickly, these connections prove invaluable.
When Traditional Methods Won't Work
Sometimes the math doesn't add up. Your home needs $30,000 in repairs to be market-ready. You don't have the cash, and you can't wait months for a traditional buyer's financing to clear. The property might carry code violations, foundation issues, or other problems that scare away conventional buyers.
Vacant properties present unique challenges. Insurance costs more. Vandalism and weather damage threaten empty homes. Winter pipes freeze. Summer humidity breeds mold. The longer a property sits vacant, the more problems emerge. If you've inherited a house in Evansville and live three states away, managing repairs and showings becomes a nightmare.
The Cash Buyer Alternative
Cash buyers operate differently than traditional purchasers. They buy properties in any condition, eliminating the repair contingency that kills many traditional sales. No appraisal requirements mean no deal-killing low valuations. No financing contingencies eliminate the 30-45 day mortgage approval process.
The timeline compression is dramatic. Where traditional sales measure in months, cash transactions measure in weeks or even days. Companies like HudREI provide cash offers within 24 hours and can close in as little as 2-3 weeks, offering certainty when you need to sell house quickly.
Trade-offs to consider:
Cash offers typically come in 10-30% below retail market value
You save on repairs, agent commissions (typically 6%), and closing costs
Certainty replaces uncertainty-no deals falling through at the last minute
Timeline control lets you choose your closing date
Calculating Your Real Bottom Line
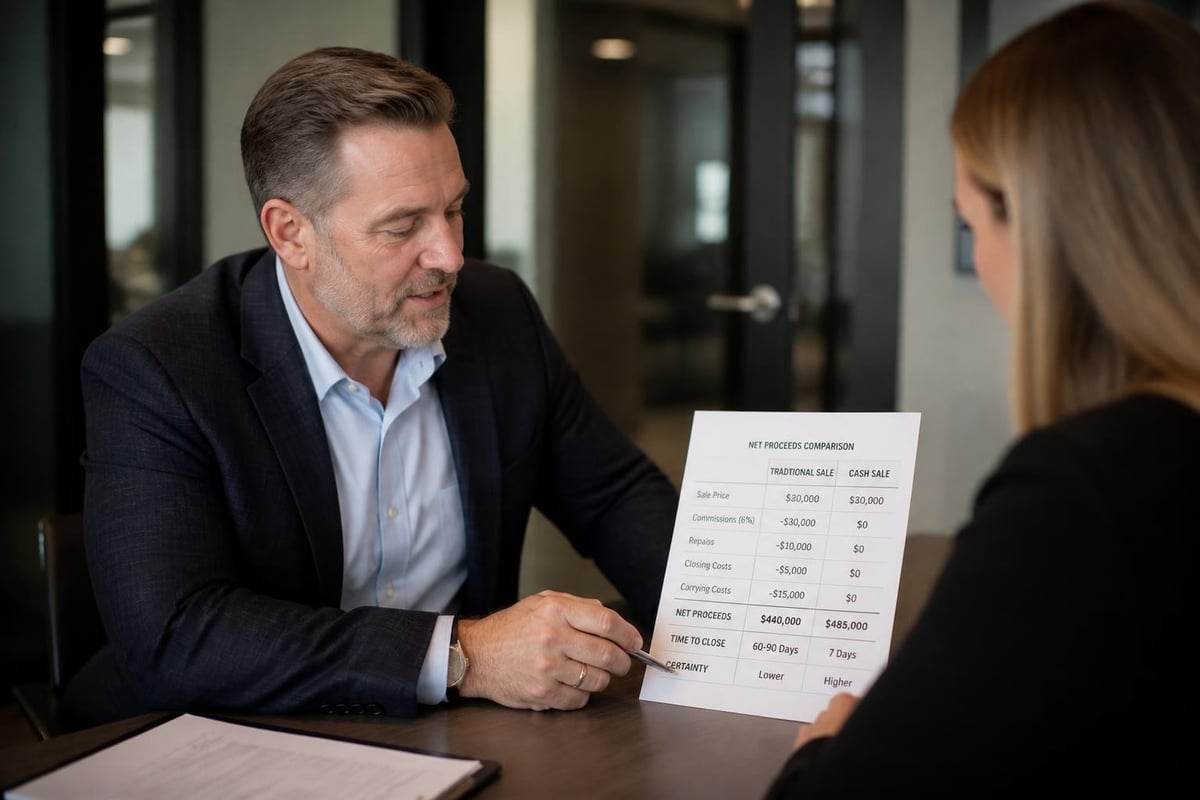
The sticker price doesn't tell the whole story. A $200,000 traditional listing sounds better than a $160,000 cash offer until you run the numbers. Traditional sales cost 8-10% in commissions, closing costs, and concessions. That $200,000 sale nets you $180,000-$184,000 after a 6% agent commission and 2-4% in other costs.
Now factor in time-sensitive costs. If you're carrying a $1,500 monthly mortgage payment, $200 in insurance, $150 in utilities, and $100 in maintenance, each month costs you $1,950. A four-month traditional sale costs $7,800 in carrying costs alone. Your $184,000 net becomes $176,200.
The $160,000 cash offer closing in three weeks carries minimal additional costs. You might net $157,000-$158,000 after minimal closing expenses. The $18,000 difference buys you certainty, speed, and freedom from repairs and showings. For many sellers facing urgent timelines, that trade-off makes perfect sense.
Sale MethodGross PriceCommissionsClosing CostsCarrying CostsNet ProceedsTimelineTraditional$200,000$12,000$4,000$7,800$176,20016 weeksCash Buyer$160,000$0$2,000$975$157,0253 weeksFSBO$200,000$0$4,000$9,750$186,25020 weeks
Geographic Considerations in Indiana
Market dynamics shift dramatically across Indiana. South Bend operates differently than Bloomington. College towns see seasonal fluctuations tied to academic calendars. Industrial cities follow employment patterns. Understanding your local market prevents costly timing mistakes.
Urban markets generally move faster than rural ones. A property in Marion County attracts more buyers than a similar home in a rural township. But rural properties often face less competition, potentially balancing the equation. The key lies in understanding your specific market's current conditions.
Avoiding Quick-Sale Scams
Desperation attracts predators. Scammers target homeowners who need to sell house quickly, offering "solutions" that create bigger problems. Common red flags include buyers who pressure you to sign quickly without review time, request unusual payment methods, or insist you pay fees upfront.
Legitimate cash buyers provide written offers with clear terms. They allow attorney review. They use reputable title companies for closing. If someone claims they can close in 48 hours but needs a $5,000 "processing fee" first, walk away. Real cash buyers make their profit on the transaction, not from fees charged to desperate sellers.
Due Diligence Protects You
Research any company before signing anything. Check their Better Business Bureau rating, read online reviews, and verify their business registration. Ask for references from recent sellers. A legitimate operation welcomes scrutiny. For instance, you can review customer testimonials to understand others' experiences.
Consult a real estate attorney before accepting any offer significantly below market value. The few hundred dollars spent on legal review protects against costly mistakes. Attorneys spot predatory terms, ensure clear title transfer, and protect your interests throughout the transaction.
Timing the Market-Or Not
Market timing debates rage endlessly. Should you wait for spring when buyers flood the market? Kiplinger's analysis of selling timing explores the many factors beyond seasons. Interest rates, local employment trends, and inventory levels all impact selling speed.
Here's the reality: if you need to sell house quickly, market timing becomes academic. You can't wait six months for optimal conditions when foreclosure looms in 60 days. The best time to sell becomes now, with strategy compensating for market conditions.
That said, understanding seasonal patterns helps. Spring traditionally brings more buyers. Summer works well for families wanting to move before school starts. Fall sees serious buyers motivated to close before year-end. Winter offers less competition but fewer buyers.
Paperwork and Legal Essentials
Speed doesn't excuse sloppy documentation. Gather essential papers before listing: deed, mortgage statements, property tax records, homeowners association documents, appliance warranties, and home improvement receipts. Having everything organized prevents delays when buyers make offers.
Critical documents checklist:
Property deed and title information
Mortgage payoff statement
Property tax bills (current and previous year)
Homeowners insurance policy
HOA documents and fee schedules
Recent utility bills
Home inspection reports (if available)
Permits for improvements or additions
Appliance manuals and warranties
Survey and plot plan
Title issues derail quick sales. Discover problems early by ordering a title search immediately. Liens, judgments, or ownership disputes take time to resolve. Finding them after accepting an offer restarts your timeline. Proactive title research identifies problems while you still have options.
The Emotional Journey
Selling quickly means compressed emotions. Grief, relief, anxiety, and hope crash together. The home holds memories-first steps, family dinners, quiet mornings. Quick timelines don't allow gradual detachment. Some sellers feel they're betraying those memories by rushing the sale.
Financial stress amplifies emotional difficulty. Making rational decisions while facing foreclosure or divorce challenges even the most level-headed people. Recognize that emotion influences judgment. Lean on trusted advisors-attorneys, financial planners, or counselors-for perspective when emotional overwhelm clouds thinking.
Letting go happens differently for everyone. Some sellers need closure rituals-final photos, goodbye gatherings, journaling about memories. Others prefer quick, clean breaks. Neither approach is wrong. Honor your emotional process while maintaining forward momentum toward your goal.
Alternative Solutions Worth Exploring
Creative financing occasionally bridges urgency gaps. Lease-to-own arrangements let you move while maintaining ownership temporarily. Seller financing attracts buyers who can't qualify for traditional mortgages, potentially speeding sales. These options carry complexity and risk but might fit specific situations.
Renting instead of selling preserves the asset while solving immediate cash flow problems. If you're relocating for work but market conditions are terrible, renting temporarily might make sense. However, becoming an accidental landlord brings its own challenges-tenant management, maintenance emergencies, and vacancy risk.
Home equity lines of credit (HELOCs) or bridge loans provide short-term cash without selling. These tools help if you need money now but expect better selling conditions soon. The debt service costs money monthly, and you'll eventually need to sell, but strategic borrowing sometimes creates better outcomes than desperate quick sales at terrible prices.
When time pressure collides with real estate, knowing your options transforms panic into strategy. Whether you choose traditional listing with aggressive tactics, explore cash buyer alternatives, or pursue creative solutions, understanding the true costs and timelines of each path enables informed decisions. If you're in Indiana and need certainty above all else, HudREI offers fair cash offers within 24 hours, no repairs or commissions required, closing in as little as 2-3 weeks on your schedule. Sometimes the fastest path forward is also the smartest one.